Mobile mechanic insurance, with no shop to stand in
A mobile mechanic runs a shop with no premises: the liability travels to every driveway and parking lot, the van needs commercial auto coverage of its own, and the tools inside are property in motion. Even the garage trade's custody question reads differently when the customer's car never actually enters your shop.
Garage liability vs garage keepers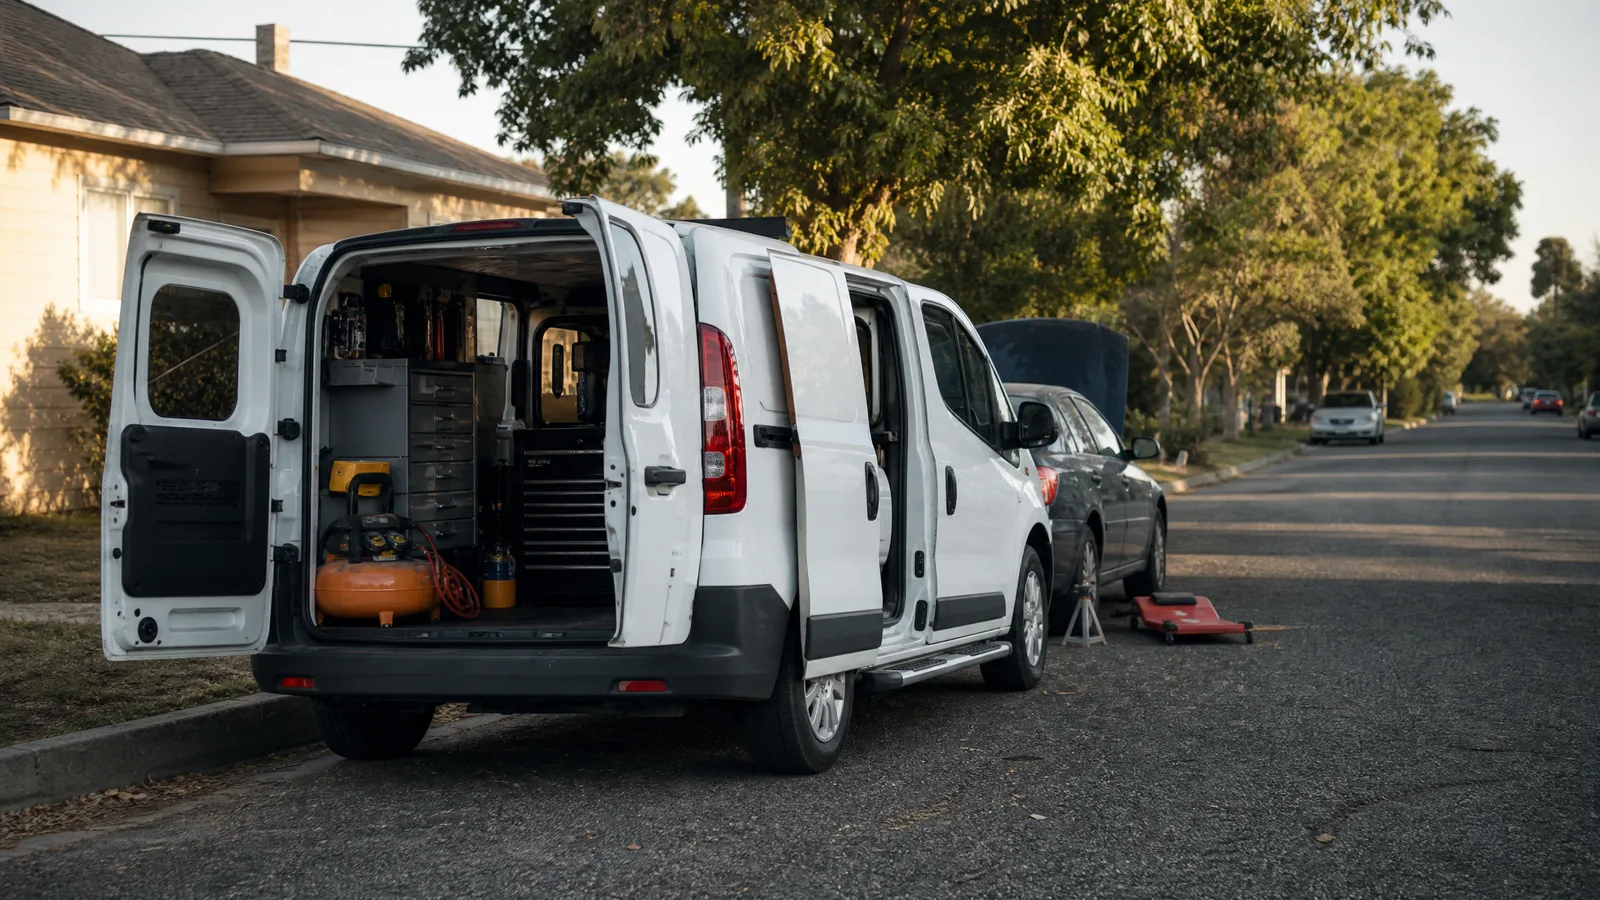
Liability without a premises
The liability core is the standard one, relocated. General liability covers the NAIC's categories, bodily injury and damage to others' property in front (NAIC, Insure U: Small Business Insurance), and for a mobile operation the "premises" is wherever the van parks: a customer's driveway, an office lot, a roadside shoulder. The claims are ordinary service-work claims, a jack that slips, a spill that stains, an injury near the work, happening on premises you neither own nor control, which is exactly what the coverage is for.
The custody question is where mobile work genuinely differs from the shop trade. Garagekeepers coverage exists for damage to a customer's auto left in your care (IRMI), and a driveway repair mostly is not that. Mostly. Test drives, repositioning a car, or hauling one to your own space for a bigger job all put a customer's vehicle under your control, and how the form treats those moments is a question to put to the agent in those words. The full decision logic is on our garage liability vs garage keepers page.
The van, the tools, and growing into a bay
The van. The NAIC's guidance is direct: a business that owns or leases a vehicle needs commercial auto coverage, personal policies may exclude business-related liability, and commercial policies carry higher limits (NAIC). A liveried van full of equipment is business use every mile.
The tools. Diagnostic gear and a full tool complement can be the operation's largest asset, and it lives in a vehicle rather than a building. Premises property coverage handles traveling equipment unevenly, so ask specifically about tools in transit and theft from the van. Know both answers, vehicle and contents, before either claim happens.
Growing. A mobile operation that takes a bay, hires a second tech, or starts holding vehicles overnight has become a shop, and the fuller stack on auto repair shop insurance applies, workers compensation included, required in nearly all states once you employ. A one-person operation weighing where it sits should also read mechanic insurance, which covers the individual-versus-shop framing. Or start at the overview.